

TCC Group Holdings, the Taiwan-based cement and building materials group known as TCC, is moving to acquire Ukraine's second largest cement producer in a deal valued at up to €750 million (about US$857 million).
S&P Global Ratings and Taiwan Ratings both left TCC's credit ratings unchanged after reviewing the proposed purchase, saying the group can absorb the additional debt without a significant weakening of its capital structure.
Board Approves Up To €750 Million Ukraine Bid
TCC's board approved the plan at a special meeting on September 23. It authorized the company's Dutch subsidiary, TCC Group EMEA Holdings B.V., to pursue the acquisition at an enterprise value of up to €750 million.
The deal covers 100% of Ivano-Frankivskcement (IFCEM) and three related companies: Ivano-Frankivsk-Dakh, which makes roofing materials; KRU Gips, a gypsum producer; and KRU Mix, a maker of dry-mix mortar. TCC Vice President Shelly Yeh said the final price will be adjusted at closing for factors such as net debt and net working capital.
The transaction still needs regulatory approval in Taiwan, Ukraine and other jurisdictions, and TCC has not announced a completion date. The company has said the purchase would extend its European cement business eastward and position it to take part in Ukraine's eventual reconstruction. It also plans to bring lower-carbon cement technology to the business to improve its export competitiveness under European Union carbon rules.
IFCEM Holds About 36% Of Ukraine's Cement Market
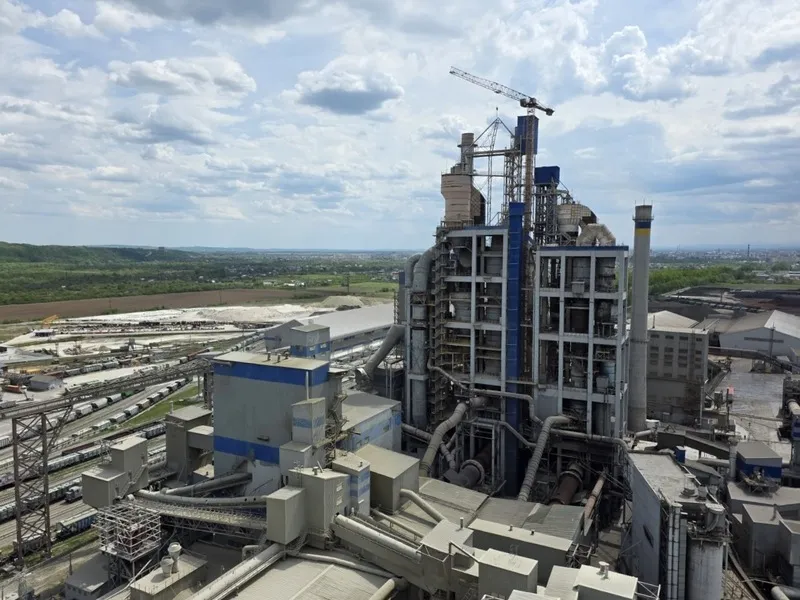
IFCEM is based in Ivano-Frankivsk in western Ukraine and holds about 36% of the country's cement market. It also sells to Poland, Romania, Moldova, Slovakia and Hungary. Its revenue in 2025 was 16.25 billion hryvnias (about US$362 million), up 20.3% from a year earlier, according to Taiwan's Central News Agency.
The Kyiv Independent has reported that Ukraine has only three active cement producers, and that reconstruction could require 15 million to 16 million metric tons of cement a year. War has destroyed or occupied five cement plants since 2014, the outlet said.
Rating Agencies Say TCC Can Absorb Added Debt
S&P Global Ratings and Taiwan Ratings, S&P's affiliate in Taipei, each issued separate commentary on the deal. Neither changed TCC's existing ratings or outlook. S&P rates the company 'BBB-' with a stable outlook, while Taiwan Ratings rates it 'twA+', also with a stable outlook.
S&P said the acquisition should modestly improve TCC's geographic diversification in Europe and that the group can take on the extra borrowing without materially weakening its capital structure. Taiwan Ratings said the deal would expand TCC's European footprint despite higher operating risk in Ukraine, and that the group should be able to absorb the added debt. Both agencies noted that Ukraine's postwar reconstruction could bring further business opportunities.
The two agencies estimate that TCC's ratio of debt to EBITDA, a measure of earnings before interest, taxes, depreciation and amortization, will rise from 2.5 times for the 12 months ended June 30, 2026, to about three times in 2027 and 2028 once the deal is included. That is still consistent with its current ratings, and the earnings the acquired businesses generate should help limit the increase.
War Risks Linger Despite Plant's Distance From Frontlines
Both agencies cautioned that the war still poses potential risks to production, logistics, power supply, assets and workforce in Ukraine. They said currency volatility and capital controls also require continued monitoring.
S&P noted that IFCEM's operating sites are far from the main combat zones and that the company has so far suffered relatively limited disruption.
(Related:
Maker of Ukraine's Killer Drone Lands in Taiwan
|
Latest
)