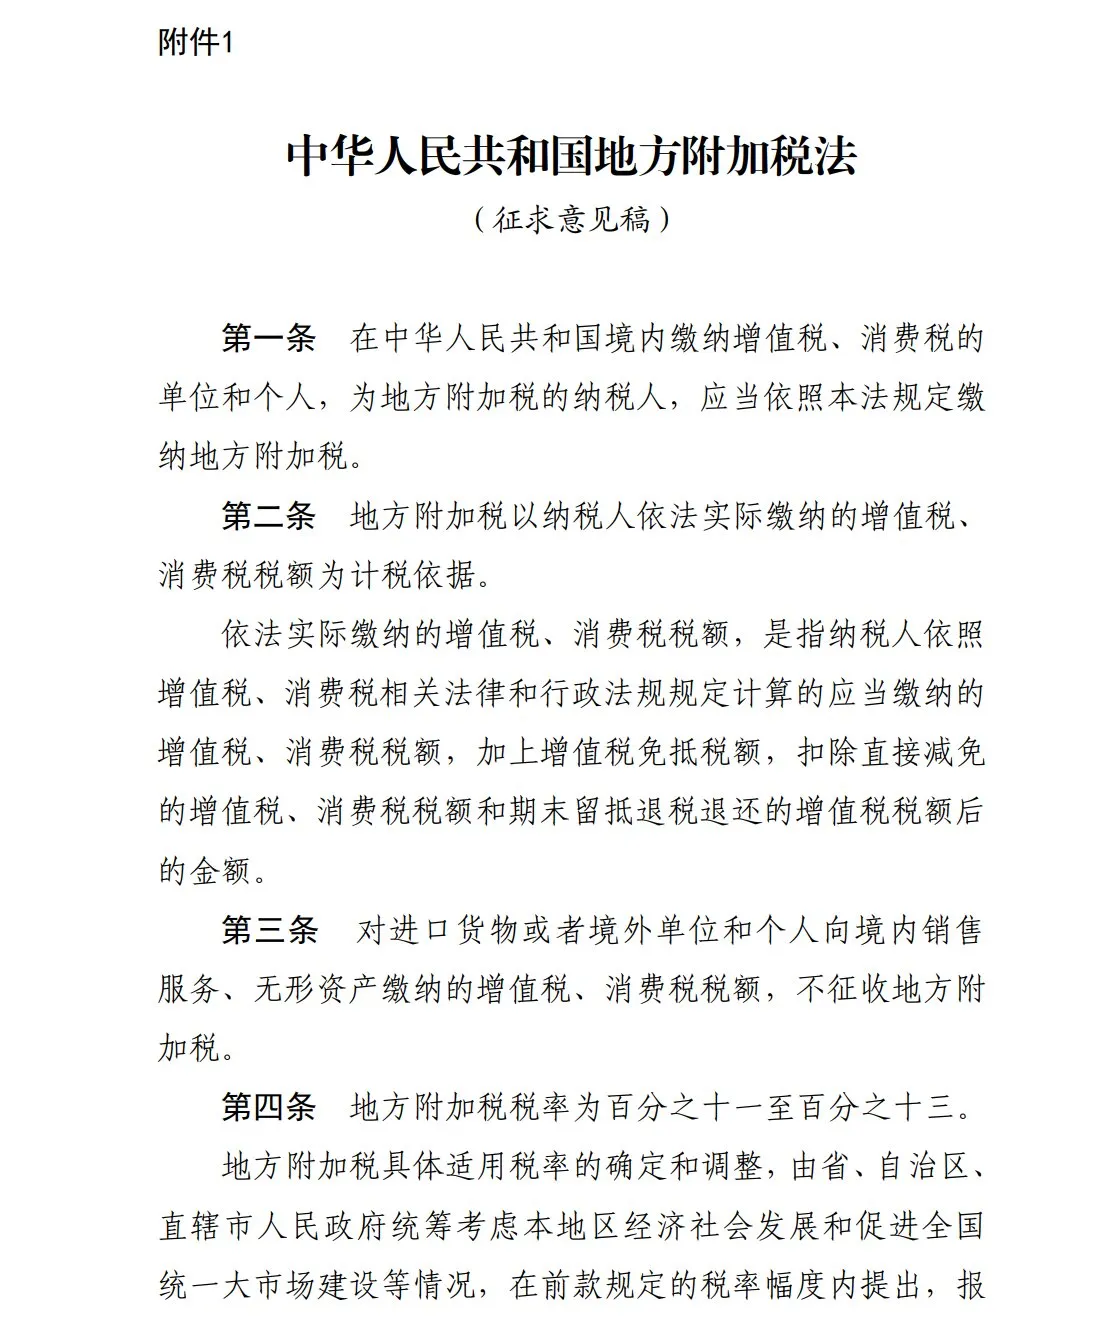
China's Ministry of Finance and State Administration of Taxation released a draft Local Surtax Law for public comment on August 28, proposing to consolidate three existing levies into a single tax set at between 11% and 13% — a reform that could significantly raise operating costs for businesses based outside China's major urban centers.
The draft, open for public comment until September 27, merges the Urban Maintenance and Construction Tax, the Education Surcharge, and the Local Education Surcharge — collectively known in Chinese tax practice as "one tax, two fees" — into a unified Local Surtax. Provincial governments would set their own specific rate within the 11%–13% range, subject to approval from the corresponding provincial legislature. The legislation is classified as a Category I priority in the 14th National People's Congress Standing Committee's five-year legislative plan, signaling Beijing's intent to move it through the legislative process on an accelerated timeline.
Three Levies Become One — With a Higher Floor for Rural Factories
Under the current system, the combined rate varies significantly by location: businesses in urban areas pay roughly 12%, those in county-level cities and towns about 10%, and those in remote areas as little as 6%. The draft's new floor of 11% would leave urban businesses largely unchanged or slightly better off, but would represent a steep increase for factories in rural and semi-urban locations currently paying far less.
The tax base remains unchanged — calculated on actual VAT and consumption tax paid, not on gross revenue, a point officials have emphasized to counter concerns about overreach. The three levies generated a combined 913.4 billion yuan in 2025, making them a significant component of local government finances.
A notable structural change: revenue previously earmarked for education would be folded into general local government funds available for broader use. This gives local governments more fiscal flexibility but removes the dedicated character that the education surcharges previously carried. Once enacted, the new law will also supersede the existing Urban Maintenance and Construction Tax Law.
Why Beijing Is Overhauling Local Finance Now
The reform reflects the pressures bearing down on local government finances across China. Land sale revenues — long the backbone of local budgets — have contracted sharply as the property market has remained in a prolonged downturn. Local governments continue to carry heavy responsibilities for public services, infrastructure, and debt repayment, creating a structural mismatch between revenues and expenditures.
The draft law follows directives from the Third Plenary Session of the 20th Central Committee and fits into a broader push toward formalizing tax collection. China's VAT Law took effect in January 2026, and the fourth phase of the Golden Tax System (金稅四期) — the country's digital tax administration platform — has continued to sharpen enforcement. Together, these moves signal a shift from ad hoc local incentives and informal arrangements toward a more standardized, rule-based fiscal regime.
By authorizing provincial governments to set rates within a defined band, Beijing simultaneously tightens central control over the overall range while granting localities a modest degree of fiscal self-determination. Local governments gain a more stable revenue stream; in return, they lose the flexibility to offer deep, unilateral tax concessions to attract investors.
Taiwan Manufacturers Face Uneven Impact Across China's Regions
For most Taiwan-invested manufacturers operating in China — paying VAT and consumption tax in the normal course of business — the Local Surtax is not an entirely new burden. The taxpayer scope and tax base largely mirror the existing system, and officials have indicated that preferential policies for small and micro enterprises will be preserved in principle.
The real impact is structural rather than aggregate. Many Taiwan-invested factories are not in city centers — they tend to cluster in county-level industrial parks across the Pearl River Delta and Yangtze River Delta, or in newer manufacturing bases in central and western China, where the current effective rate can be as low as 6%. The new 11% floor represents a direct cost increase for these facilities, even if businesses in major urban centers see little change or a slight reduction.
The compression of the tax band — from a previous spread of roughly 6%–12% down to a narrow 11%–13% — also reshapes how localities compete for investment. Local governments have long used tax concessions as an attraction tool. With far less room to differentiate on taxes, wealthier provinces may sustain lower rates to stay competitive while fiscally stressed localities push toward 13%. This dynamic could complicate the calculations of Taiwan companies with plants spread across multiple provinces.
Thin Margins Leave Little Room to Absorb New Costs
For large Taiwan enterprises, a one-percentage-point shift in surtax rates may register as a minor variable in a financial model. For smaller manufacturers operating on thin margins in competitive sectors, any fixed cost increase carries far greater weight.
Compounding the issue is China's weak domestic demand. In an environment where companies are competing aggressively on price, additional tax costs are more likely to be absorbed into profit margins than passed on to customers. That dynamic turns what looks like a modest policy adjustment into a meaningful earnings pressure for businesses already managing tighter operating conditions.
The draft remains open for comment until September 27. Whether the final law maintains the current rate structure or adjusts it in response to feedback from businesses and local governments remains to be seen. (Related: Beijing Watch | China's Tax Sweep Targets Hong Kong Insurance Policies | Latest )
Original Article In Chinese: https://www.storm.mg/article/11160647#wholePage