Japan placed two landmark bets on rare earth independence in 2026 — government-backed deep-sea mining near its most remote Pacific island and a ¥35 billion joint refinery with chemical giant Shin-Etsu Chemical — but ambition alone cannot substitute for the grinding, decades-long work of building a supply chain that China has spent a generation perfecting.
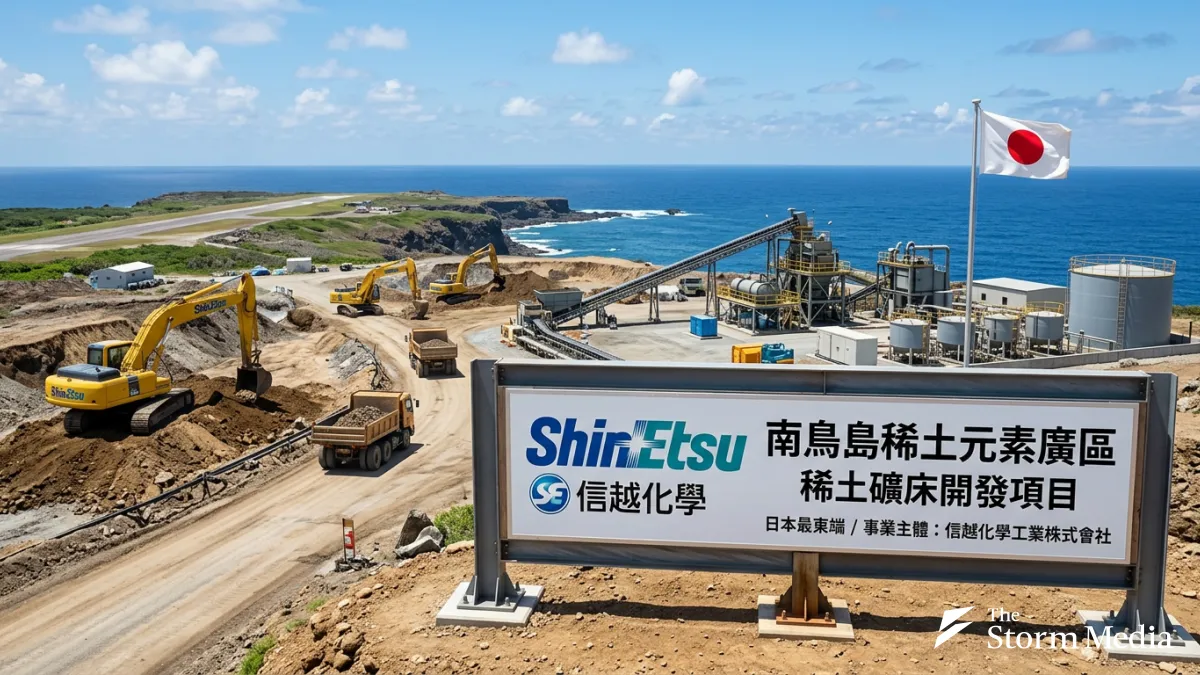
The two announcements came months apart. On February 3, Japan's Ministry of Economy, Trade and Industry declared that state funds would back industrial-scale extraction of rare earth mud from the seabed around Minamitorishima Island, with subsidies covering both mining and smelting. On June 11, the government and Shin-Etsu announced a joint ¥35 billion venture — each side contributing ¥17.5 billion — to build a new heavy rare earth refinery in Echizen City, Fukui Prefecture. The stated goal: industrial autonomy in a sector where China's grip has proved, for 16 years, essentially unbreakable.
China's Export Ban and the Taiwan Factor
Japan's rare earth anxiety is not new. The 2010 Senkaku Islands standoff produced the first high-profile Chinese rare earth shock, and Tokyo has been searching for alternatives ever since. What hardened political resolve this time was a trigger directly linked to Taiwan.
When Japan's government declared that "Taiwan's affairs are Japan's affairs," Beijing responded by tightening export restrictions on dual-use materials, including rare earths. The impact was nearly immediate — Japanese manufacturers found supply pipelines running dry, and Shin-Etsu's own factory in Fujian's Changting was effectively cut off from supplying intermediate products back to its Japanese parent plants.
The International Energy Agency projects that even with aggressive diversification, roughly 80% of the world's refined magnetic rare earth products could still come from China as late as 2035. That number captures the structural depth of the problem Japan is now trying to solve — and the scale of what "independence" would actually require.
The Seabed Deposit That Upended Japan's Expectations
Minamitorishima — sometimes called Marcus Island in English — is a speck of Japanese territory measuring just 1.52 square kilometers, administered by Tokyo's Ogasawara village but positioned more than 1,900 kilometers from the capital, surrounded by open Pacific in every direction for 1,000 kilometers.
The island's rare earth story traces back to July 3, 2011, when University of Tokyo professor Yasuhiro Kato published a paper in Nature Geoscience identifying Pacific deep-sea mud as a potential large-scale rare earth resource. Kato's research was not yet complete at the time of publication — he released it early, partly to give Japan diplomatic leverage and boost domestic morale during the escalating 2010 rare earth confrontation with China.
What followed was a systematic scientific narrowing of focus. By 2013, Kato's team had confirmed the highest-concentration rare earth mud deposits ever recorded anywhere, sitting within Japan's own exclusive economic zone around Minamitorishima. The peak REY concentration — rare earth elements plus yttrium — reached 6,600 parts per million, roughly 20 to 30 times richer than China's onshore ion-adsorption deposits, with high-grade layers lying just meters below the seabed surface. A 2018 estimate put total resources at approximately 16 million tons of rare earth oxides, with especially strong concentrations of strategically critical heavy rare earths: yttrium, dysprosium, and terbium.
In July 2026, Japan's Cabinet Office and JAMSTEC, the Japan Agency for Marine-Earth Science and Technology, reported successfully collecting about 50 tons of deep-sea sediment from between 5,600 and 6,000 meters below the surface. Analysis found that heavy rare earth elements accounted for 54% of the material — and crucially, no toxic or radioactive substances were detected. Large-scale trial mining is planned for February 2027, preliminary commercial production in 2028, and full industrial output within three years after that.
Engineering the World's First Deep-Ocean Rare Earth Mine
The resource numbers are extraordinary. The engineering reality is daunting.
No country has ever commercially extracted rare earths from the deep ocean floor. Japan must engineer from scratch an entire system capable of operating under 600 atmospheres of water pressure — equivalent to 600 kilograms of force per square centimeter — at 6,000 meters. Collector vehicles, lift pipes, deep-sea robotics, and offshore platforms are all still in testing phases. Even deploying vessels like the drilling ship Chikyu to relay hundreds of ultra-high-strength pipes to the surface involves technical complexity with no precedent.
Geography compounds every challenge. Support operations must travel nearly 2,000 kilometers from the Japanese mainland. Typhoon seasons impose unavoidable operational gaps. And the economics are stark: current extraction costs are estimated at roughly 20 times what China pays for land-based mining. The 2027 daily extraction target stands at 350 tons — meaningful progress, but the project would need 3,500 tons per day to reach break-even. The gap between those two numbers is where strategic narrative meets economic reality, and it is a gap that no amount of national resolve can simply will away.

Why Shin-Etsu Is the Ideal Partner but Cannot Solve the Hardest Problem
Shin-Etsu Chemical brings 60 years of rare earth expertise to the Echizen refinery, along with the world's most advanced multi-stage solvent extraction and separation technology. Its Takefu plant pioneered samarium-cobalt magnets in 1976 and neodymium-iron-boron sintered magnets in 1985. A proprietary grain boundary diffusion technique allows the use of extremely small quantities of dysprosium and terbium to produce heat-resistant permanent magnets — technology that has made Takefu a de facto global destination for the electromagnetic industry.
One flagship product, 6N-grade yttrium oxide refined to 99.9999% purity, is an irreplaceable input for plasma-resistant coatings on semiconductor fabrication equipment, particularly at 3-nanometer process nodes and below, where any metallic contamination causes wafer failure and scraps entire production runs.
The new Echizen plant will focus on heavy rare earths — dysprosium, terbium, and yttrium — processing from raw ore and working in tandem with Takefu Plant 1 for separation and refining and Takefu Plant 2 for magnet raw material production and recycling, forming what would be Japan's first genuinely integrated heavy rare earth production system.
But building the refinery is the easier half. Feeding it is not.
Five Structural Hurdles That Will Determine the Outcome
The largest risk facing the Echizen plant is not technical — it is feedstock. Japan's domestic territory contains virtually no commercially viable rare earth deposits. The new refinery will depend on ore imports from Australia's Lynas, the United States, Vietnam, India, and Brazil, all sources that other countries are simultaneously competing for, and each of which faces its own extraction quality constraints and environmental approvals. The most strategically critical heavy rare earths — dysprosium and terbium — remain overwhelmingly dependent on Chinese supply, and China's 2025 export restrictions have already demonstrated how quickly that dependence can become a crisis.
Shin-Etsu is supplementing imports with domestic recycling. In April 2026, it announced Japan's first national closed-loop recycling program for commercial air conditioning compressor magnets, developed in partnership with Daikin, Hitachi, and Tokyo Eco Recycle. Japan's large and sophisticated electronics and industrial machinery sectors generate significant rare earth waste streams; recovered material could eventually contribute meaningfully to supply. But not fast enough, and not at the volumes that full independence would require.
Heavy rare earth separation is chemically exhausting. Separating dysprosium, terbium, and yttrium requires hundreds of extraction stages, massive quantities of chemical agents, and near-perfect process control. Any lapse in quality cascades into collapsing purity levels and surging costs. The larger the plant, the harder the control problem becomes — and producing the stable, high-volume, low-cost intermediate products that China currently supplies at scale remains an entirely different challenge from the precision high-purity work where Shin-Etsu already excels.
China, which still controls the majority of global rare earth separation and refining capacity, has repeatedly used selective market flooding to undercut Western competitors the moment they approach commercial viability. Japan's new plant will need either robust financial reserves or government price guarantees and long-term purchase contracts to survive a deliberate price war. The playbook is well-established; the countermeasures are still being drafted.
Environmental compliance costs in Japan are substantially higher than in China, where the world's most polluting initial and mid-stage rare earth processing has historically been concentrated in lower-regulatory-cost locations. Rare earth refining generates hazardous acid waste and, in some ore types, trace radioactive elements including thorium and uranium. Shin-Etsu chose the Echizen site partly because its existing infrastructure already includes mature radioactive materials management systems — keeping expansion costs lower than a greenfield site. But as the plant extends upstream toward raw ore processing, which is necessary for genuine supply chain independence, the environmental footprint expands into territory that could face regulatory and public pushback under Japan's comparatively stringent national standards.
Finally, the global talent shortage in rare earth processing is severe. Specialized solvent extraction engineers, analytical chemists, and high-purity quality control experts are in acute shortage not just in Japan but across every Western economy attempting to exit China's supply chain. China has deliberately restricted exports of not just products but also personnel, equipment, and solvent chemical formulas — a knowledge embargo that no country has yet found a systematic way around.
Whether Resolve Can Outlast Reality
Minamitorishima and the Echizen refinery are not standalone solutions; they are the two most visible bets in a longer-odds, longer-timeline strategy. Japan has spent 16 years and considerable national resources attempting to reduce rare earth dependence on China, with limited success. That history warrants caution about declaring the latest round of investments transformative.
What has genuinely changed is the political calculus. China's sweeping 2025 restrictions — covering not just rare earth products but the surrounding infrastructure of knowledge, logistics, and personnel — have removed the last illusion that market mechanisms alone will provide a reliable buffer. The Taiwan connection has made that calculation tangible and urgent in a way that decade-old Senkaku disputes did not.
As the author, who serves as convener of the Taiwan Rare Earth and Rare Resources Application Industry Alliance, argues: whether Japan succeeds in breaking free from China's chokehold depends less on the richness of the seabed or the sophistication of Shin-Etsu's chemistry than on whether governments can sustain financial and political commitment long enough for a genuinely independent supply chain to mature. That is a question about institutional endurance, not technical ingenuity — and it may be the hardest problem of all.
The world is watching. And so is Taiwan, whose own security calculus is woven through every stage of this unfolding rare earth reckoning.
*The author is the convener of the Taiwan Rare Earth and Rare Resource Application Industry Alliance.
Original Article in Chinese