From the United States to Japan, 2026 has brought a reckoning for the global offshore wind industry — what was once a race to claim clean energy ambitions has become something far more demanding: a test of industrial depth, policy consistency, and the ability to actually build.
The divergence has grown stark. The United States, once among the most aggressive proponents of offshore wind expansion, has effectively frozen new development following President Donald Trump's return to the White House. Japan is grappling with the long-term consequences of an auction system designed to extract the cheapest possible electricity tariff rather than to produce commercially viable projects. Europe is navigating supply chain stress and cost overruns while still moving major installations forward. And China, largely insulated from the political and economic turbulence affecting Western and Japanese markets, is now the dominant force across the entire Asia-Pacific region.
Trump's First-Day Order Stalls American Projects
On his first day back in office, Trump signed an executive order suspending new offshore wind leases on federal waters and ordering a comprehensive review of existing permits and approvals. The administration followed with stop-work orders targeting farms under active construction, reduced green energy tax incentives, and in some cases, offered financial inducements to developers willing to abandon projects outright. The practical result has been severe: projects that had not yet completed federal environmental review are now in limbo, with approval timelines pushed to 2027 or 2028. Several multinational energy companies have responded by terminating leases and redirecting capital toward traditional oil and gas.
The shift has transformed what were already difficult market conditions — inflation, elevated interest rates, and supply chain bottlenecks — into a problem of direct federal hostility. Industry challenges that developers in other markets can at least plan around have, in the United States, become a matter of political survival.

Developers and States Fight Back Through the Courts
Not all projects have folded. Vineyard Wind 1 and Empire Wind, two of the most prominent offshore projects along the East Coast, challenged the federal stop-work orders in court and obtained injunctions that allowed construction to resume. The Coastal Virginia wind farm, which was already over 80% complete when the administration's orders took effect, is among the rare cases to have continued without significant interruption.
State governments have moved aggressively to fill the federal vacuum. New York and California have expanded cross-state coordination on grid transmission planning and local supply chain development, using legal challenges and inter-state energy policy alliances as the primary mechanism to sustain whatever momentum remains in the sector. For now, these state-level coalitions represent the last meaningful institutional bulwark for American offshore wind.

Europe Stabilizes After Its Own Cost Reckoning
Across the Atlantic, the challenges look different in character. Europe's offshore wind sector has not faced a political reversal — it has been working through the kind of structural stress that typically accompanies rapid industrial scaling: inflation-driven cost overruns, stretched turbine supply chains, and fierce competition for the installation vessels needed to place increasingly large offshore turbines.
The difference is that Europe entered this turbulent period with decades of accumulated infrastructure and know-how. Major projects in the United Kingdom, Germany, the Netherlands, and Poland are continuing on schedule. New auction rounds are proceeding with relative stability. Governments across the region have adjusted bidding mechanisms and increased grid investment in response to earlier project cancellations, and the overall industry now appears to have passed through its most difficult adjustment phase.

Near-term pressures remain. Global supply chain prices are still elevated. Offshore grid connections are running behind in several countries. Germany, in particular, faces a credible risk of missing its 2030 capacity targets as a result of compounding delays. But the trajectory for Europe as a whole is meaningfully more stable — and commercially more predictable — than what markets in the United States or Japan are experiencing.
Japan's Lowest-Price Bidding System Leaves Developers Stranded
Japan's difficulties trace directly to institutional decisions made years earlier. When the country designed its offshore wind auction framework, the guiding objective was to produce the lowest possible electricity tariff. The problem is now undeniable: those locked-in tariffs are no longer sufficient to cover actual construction costs, which have risen sharply as global inflation, yen depreciation, and higher interest rates hit the industry simultaneously.
The consequences are concrete. Mitsubishi Corporation, one of Japan's largest trading houses, formally withdrew from three offshore wind development projects totaling 1.7 gigawatts, citing financial pressure it described as unmanageable. Offshore installations in Akita and Chiba prefectures illustrate the broader pattern: original power-price contracts signed at competitive auction levels have left developers with no realistic margin to absorb the cost increases that have swept through the global industry.

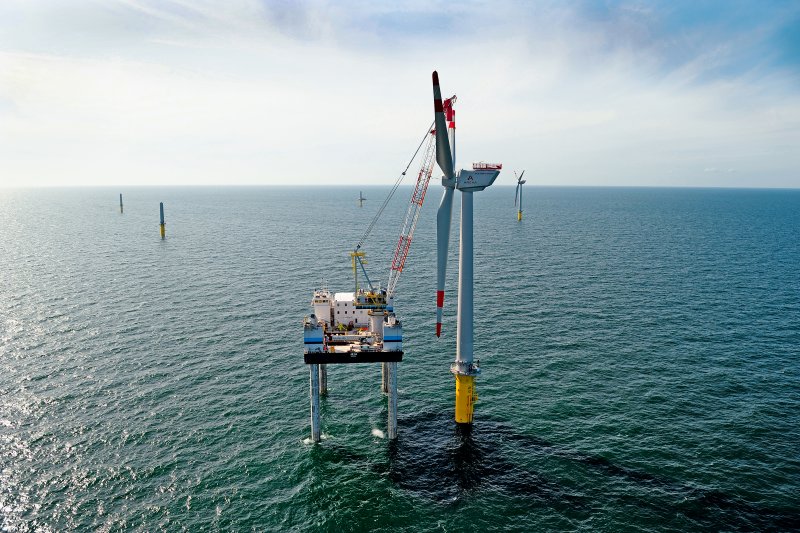
Japan does have demonstrated offshore wind operational capability — fixed-bottom facilities at Akita Port and Noshiro Port are running stably. But the commercial viability of the next generation of projects has become a question that developers are being forced to reconsider from first principles.
Tokyo Overhauls the Auction Rules to Restore Investor Confidence
The Japanese government has responded with a sweeping institutional overhaul. The revised auction framework replaces the single price criterion with a multi-factor evaluation that incorporates feasibility review indicators, supply chain resilience scoring, a government-led preliminary environmental assessment process, and electricity price adjustment mechanisms designed to reduce developers' exposure to cost volatility.
Separately, amendments to the Renewable Energy Maritime Utilization Act have expanded the legally permissible development zone from coastal waters into Japan's Exclusive Economic Zone, opening up deep-water areas where floating turbine technology would be required. Japan is already building experience in that technology through a demonstration project off Goto Island in Nagasaki Prefecture, which has entered commercial operation.
The reforms are an acknowledgment that the early institutional design failed, and a signal that the government intends to make offshore wind commercially executable again. Whether the overhaul will be sufficient to attract new investment at the scale required by Japan's long-term energy targets — 10 gigawatts by 2030, up to 45 gigawatts by 2040 — remains an open question.
China Controls Over 90% of Asia-Pacific Offshore Wind Capacity
While the United States stalls, Japan restructures, and Europe steadies, China is expanding at a pace that has fundamentally reshaped the competitive landscape across the region. Backed by a mature domestic supply chain, sustained state-owned enterprise investment, and comprehensive port and grid infrastructure, China now accounts for more than 90% of operational offshore wind capacity across the Asia-Pacific. Its installation pace continues to lead the world, and the country is actively developing both deep-water projects and the next generation of gigawatt-scale floating turbine technology.
China's structural advantage is not primarily technological. It is systemic: policy direction, capital allocation, supply chain development, and infrastructure investment operate within a single coordinated framework, eliminating the friction points that have slowed development elsewhere. When other markets are waiting for grid approvals or arguing over auction design, China is building.
Elsewhere in Asia-Pacific, the picture is more uneven. South Korea has strong industrial capacity in shipbuilding and steel and growing developer interest, but large projects continue to struggle to reach Final Investment Decision, hampered by legislative delays, restrictions stemming from its period of martial law, fishing compensation disputes, and grid construction challenges. Across Southeast Asia, markets including Vietnam, the Philippines, and India remain largely in the framework-building and resource survey stages. Unclear power purchase agreement structures and high financing costs have kept international developers in a cautious, wait-and-see posture, and large-scale physical construction is unlikely in the near term.

The Question Is No Longer Who Builds More
The clearest lesson from the current moment is that offshore wind success no longer accrues to countries with the most ambitious targets or the lowest auction prices. It belongs to those that can actually complete projects, connect them to functioning grids, manage costs through construction, and sustain supply chains capable of delivering at scale.
The United States has demonstrated how quickly a policy reversal can destroy industry confidence. Japan has shown that optimizing an auction system for the cheapest bid can render projects non-viable before a single turbine is installed. Europe is demonstrating the harder work of using institutional reform to exit a cost crisis without losing the sector. China has shown what the industry looks like when policy, capital, and supply chain are coordinated as a single system — and the advantage that creates.
For economies across the Indo-Pacific with offshore wind ambitions of their own — Taiwan included, with its own large-scale development targets and contested supply chain relationships — the global shakeout underway is not an abstraction. It is a preview of the choices they will have to make.