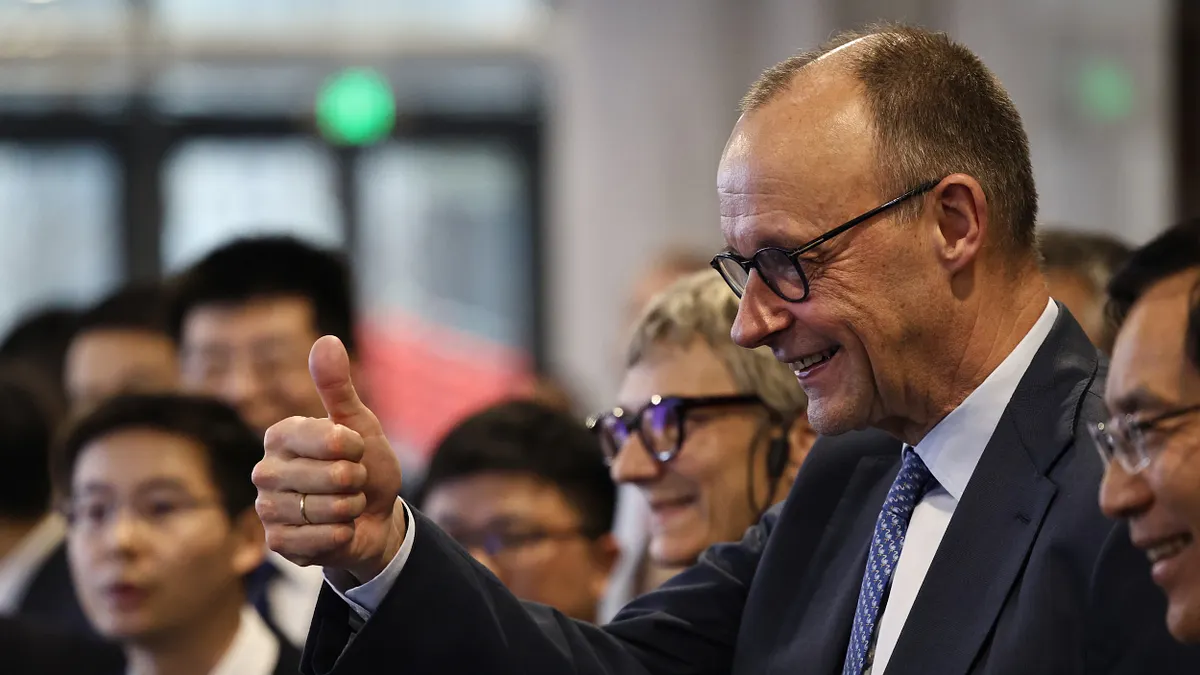
German Chancellor Friedrich Merz has concluded his visit to China, and while both sides expressed interest in strengthening cooperation and bridging differences, the fundamental divergences, competition, and conflicts between the two nations remain difficult to reconcile. This reversal in China-Germany economic and industrial dynamics offers valuable lessons that all countries should carefully consider.
A Parade Of Western Leaders To Beijing
In recent months, leaders from Britain, France, Canada, Ireland, Finland, Spain, and other Western nations have visited China with remarkably similar objectives — hedging against risks posed by Trump's policies. As Trump imposes high tariffs on all countries and disrupts global trade rules, the most rational response for nations is to strengthen ties with the world's second-largest economy and enhance bilateral cooperation. For China, which faces the greatest pressure from the trade war, this aligns perfectly with existing efforts to diversify away from U.S. dependence and strengthen economic relationships beyond America. Europe represents a key priority, offering both economic risk diversification and the strategic benefit of driving a wedge between European and American relations.
Consequently, visiting nations have returned home with political trophies for domestic audiences — market access and tariff reductions for important exports like British whisky and Canadian agricultural products, or major procurement commitments such as increased Airbus orders promised to both France and Germany.
Germany's Exceptional Exposure
However, Germany's situation differs fundamentally from other countries. Setting aside cultural and political system contradictions, Germany faces far more severe and irreconcilable economic and industrial conflicts with China than other Western nations. Both Germany and China are manufacturing powerhouses whose exports consist primarily of manufactured goods.
Most economic development follows a progression from primary industries (agriculture, forestry, mining) to secondary industries (manufacturing, industry), and finally to tertiary industries (services, knowledge industries). Advanced Western economies have long transitioned to service-dominated structures, with manufacturing's share continuously declining. In Britain, America, and France, manufacturing represents only about 10% of GDP, while the European average stands around 15%.
Germany stands as the sole exception: manufacturing accounts for a remarkable 30% of GDP, and the economy remains heavily trade-dependent, with exports consistently maintaining around 45% of GDP. This makes Germany the EU's most export-oriented economy, with machinery, transportation equipment (automobiles), and chemicals comprising over 60% of exports. By contrast, other advanced nations like Britain, France, and America have lower export-to-GDP ratios and higher service components in their export mix.
From Partners To Rivals
China dominates global manufacturing, accounting for over 30% of worldwide production, while exports serve as a crucial engine of Chinese economic growth, making it the world's largest exporter. When China and Germany maintained significant technological gaps and different specialisations, the two countries coexisted peacefully. China even became Germany's primary market, with German automotive giants Bayerische Motoren Werke AG (BMW), Mercedes-Benz, and Volkswagen deriving 30-40% of their revenues from China at peak periods, while China imported German machinery and equipment.
This harmonious relationship has fundamentally changed in recent years. Chinese manufacturing has successfully advanced toward higher technology and upstream positioning, transforming the relationship from complementary cooperation into direct competition — competition that has left Germany retreating across multiple fronts. The automotive industry, Germany's pillar sector and a source of national pride showcasing "German engineering," exemplifies this dramatic shift.
The Fall Of German Automakers
Chinese domestic car brands long struggled to exceed 40% market share in China's automotive market, a threshold observers considered the ceiling for domestic manufacturers. In 2020, this share even fell to 38%, during the height of German automotive dominance in China. Within just a few years, however, two factors
dramatically altered this landscape: the rapid shift toward new energy vehicles, where China enjoyed the advantages of a late mover able to leapfrog on the curve, and remarkably fast technological progress by Chinese automakers.
By 2025, Chinese brands captured 70% of the domestic market, while German and Japanese manufacturers suffered steep declines. Between 2022 and 2025, BMW, Mercedes-Benz, and Volkswagen saw their Chinese market shares plummet by 30-40%.
Japanese brands fared no better — Honda's Chinese sales collapsed from over 800,000 units to 300,000 within five years. Simultaneously, China surpassed Japan to become the world's largest automotive producer and exporter.
Confrontation Neither Side Can Afford
This illustrates the irreconcilable nature of German-Chinese economic relations: Germany's economic and industrial core directly competes with China's rising industries that are aggressively expanding overseas. While other Western leaders visiting China maintain cordial relations with minimal lecturing, Merz spoke frankly about fair competition, transparent rules, government subsidies, and currency undervaluation — issues that strike at the heart of Germany's core economic interests.
Yet Germany and China cannot afford direct economic confrontation due to deeply intertwined industrial and supply chain relationships. All businesses advocate engagement over separation, with German corporations actually increasing their Chinese investments significantly. This vast market simply cannot be abandoned, explaining why Merz led a massive economic delegation to China.
A Lesson Every Nation Must Heed
Germany's industrial and technological leadership — once holding a commanding lead far ahead of China — has been caught up with and in some respects surpassed within less than a generation. While external factors contributed — the Russia-Ukraine war and nuclear phase-out eliminated cheap energy, while electric vehicles and new energy technologies gave China the opportunity to leapfrog established German industries — the real causes lie in Germany's internal factors, as suggested by Merz's remarks upon returning home.
For other countries, including Taiwan, the future trajectory of China-Germany relations may matter less than the stark lesson of how Germany fell from a position of seemingly unassailable industrial dominance to being overtaken. That is a lesson that demands careful study — and urgent reflection.